
When it comes to auto insurance, most people focus on liability coverage – the part that protects others if you’re at fault in an accident. But what about protecting yourself and your passengers? That’s where Personal Injury Protection (PIP) comes in, and in Texas, it’s important coverage you’ll want to understand.
What Is PIP Coverage?
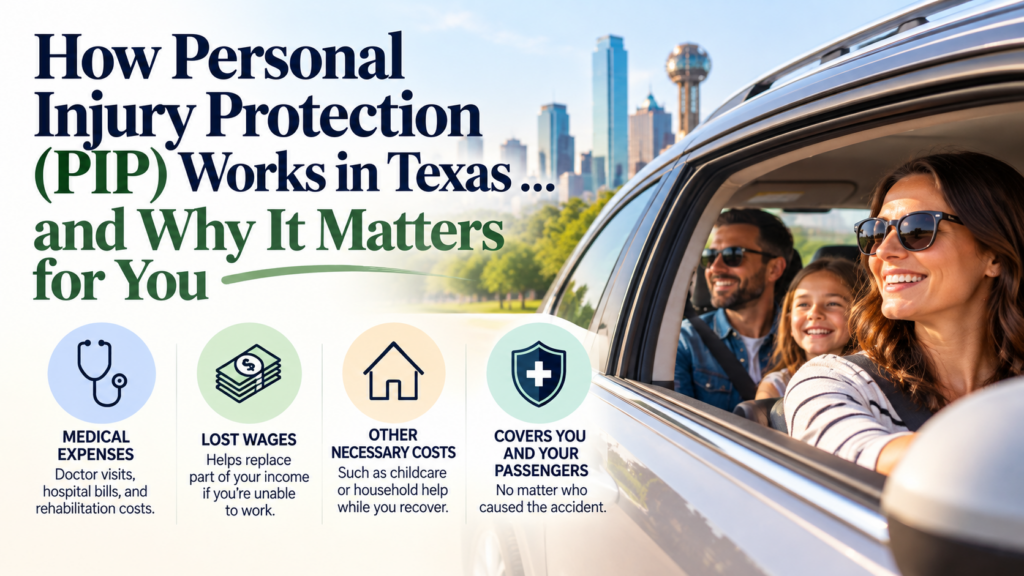
Personal Injury Protection is extra coverage on your auto policy designed to help you and your passengers, no matter who caused the accident. It’s a financial safety net that covers expenses you may not think about until you’re in the middle of a stressful situation.
What PIP Covers:
- Medical expenses – Doctor visits, hospital bills, and rehabilitation costs.
- Lost wages – If your injuries keep you from working, PIP can help replace part of your income.
- Other necessary costs – Things like childcare or household help while you recover.
How PIP Works in Texas
Every Texas auto policy automatically includes $2,500 in PIP coverage. You can choose to increase that limit for stronger protection, or—if you don’t want it—you must reject it in writing. Many people don’t realize they have options here, and understanding those options is key to making sure your coverage truly fits your needs.
Think of PIP as your financial cushion. It steps in when life gets messy, so you don’t have to dip into your savings or worry about how you’ll cover unexpected costs after an accident.
Real-World PIP Examples
Example 1: Standard $2,500 PIP Coverage
Imagine you’re driving home from work and another car runs a red light, hitting your vehicle. You suffer a minor injury that requires a trip to the ER and a week off work to recover.
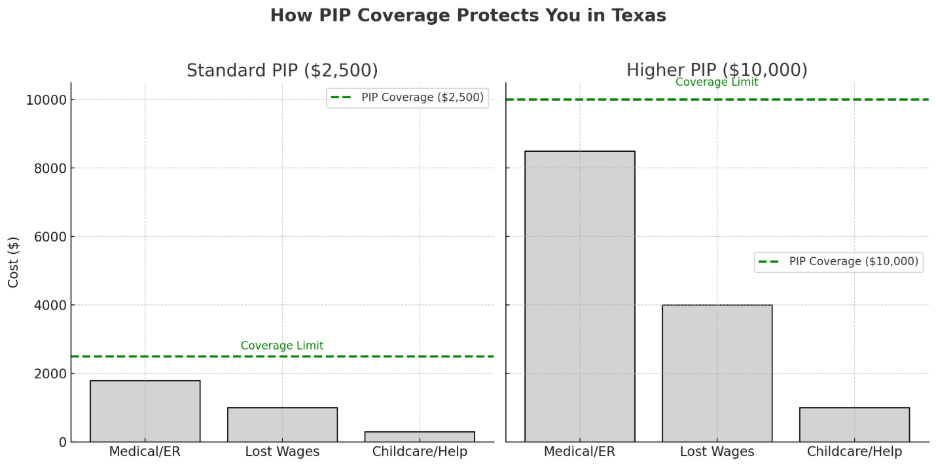
- The ER visit and follow-up care add up to $1,800.
- You also miss a week of work, costing you $1,000 in lost income.
- During that time, you need extra childcare help so you can rest, costing another $300.
That’s $3,100 in expenses. Without PIP, much of that would come out of your pocket. With PIP in place, your $2,500 coverage helps cover most of the costs, leaving only a small balance for you to handle.
Example 2: Higher $10,000 PIP Coverage
Now imagine a more serious accident. You break your leg, requiring surgery and physical therapy.
- Hospital bills and surgery total $8,500.
- You miss a month of work, losing $4,000 in income.
- You also hire help around the house and childcare, adding another $1,000 in expenses.
That’s $13,500 in expenses. With only $2,500 in PIP, you’d still face over $11,000 in out-of-pocket costs. But with a higher $10,000 PIP limit, most of those expenses would be covered—significantly easing your financial burden during recovery.
Why Work With an Insurance Expert
Coverage details like this are easy to overlook—but they can make a huge difference when you need them most. That’s where I come in. I help my customers look beyond the basics, explain what coverages like PIP actually do, and make sure your policy works for your real-life situation, not just what’s required by law.
📞 Want to see if your PIP limits are enough? Give me a call at 972-564-3333, and we’ll review your coverage together.